Why Small Businesses in the U.S. Struggle With Rising Operating Costs and What They Can Do
This article explains why many U.S. small businesses are paying more to run every month in 2026. It covers tariffs, health insurance, hiring, borrowing cost and low cash. Then it gives practical steps owners can try, how to check if they work and when they may not be enough.
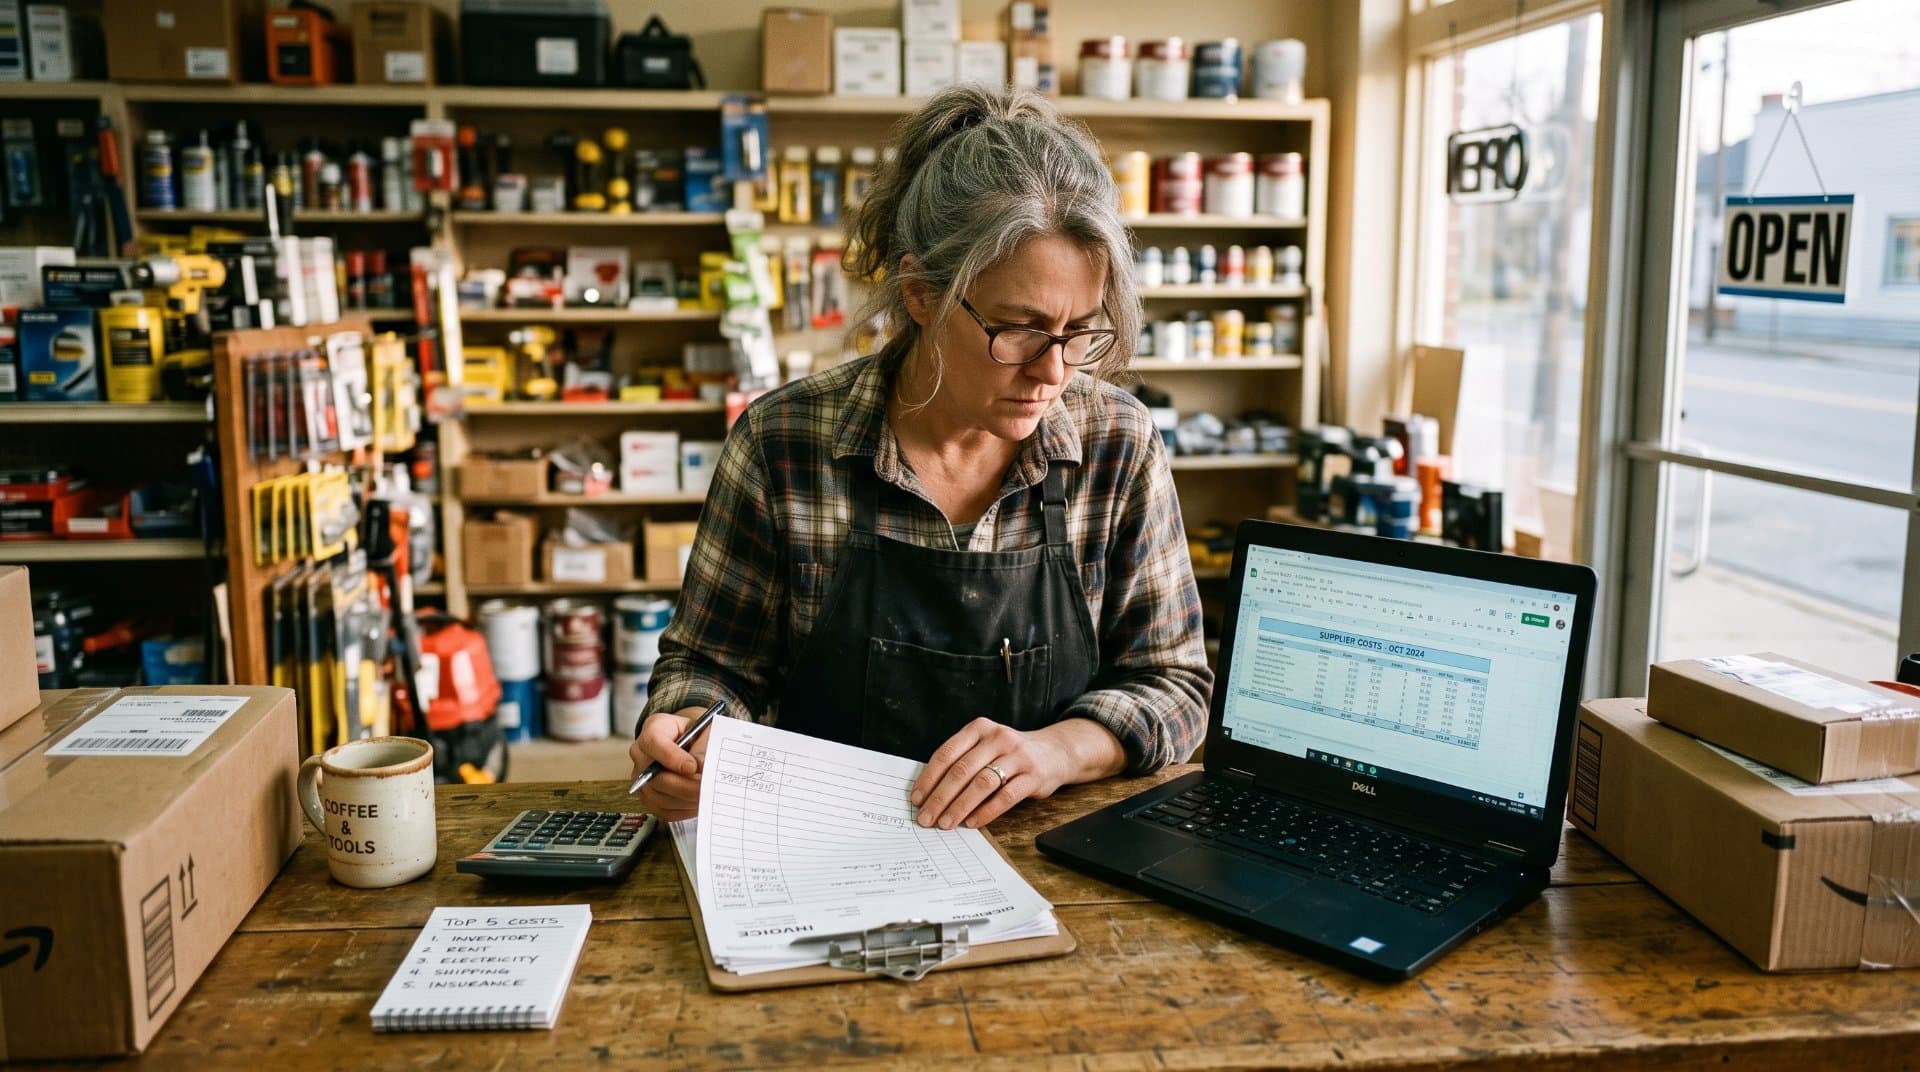
Many small business owners open the monthly bills and see the same story. Supplies cost more. Health insurance cost more. Loan payment cost more. But customers are not always ready to pay higher prices. This article explains why it is happening in 2026 and what an owner can really do about it.
Disclaimer: Information below is current as of October 2026. Some numbers change fast, so check again before you make big decisions.
The Problem
Costs go up from many sides at the same time. That is the hard part. It is not one big bill you can fix and forget.
Inflation is still there. The U.S. consumer price index was up 3.4% year over year in August 2026. In the NFIB survey for August, 16% of owners said inflation was their single biggest problem, tied with taxes for second place.
Money is also tight inside many businesses. In a February 2026 survey by lender Revenued, 75.6% of 307 owners said costs were higher than a year before and 62.9% had less than 3 months of operating cash. That is a small survey, so don't treat it like a full census. But it matches what other surveys show.
When prices rise, owners do hard things. In a March 2026 poll of 247 owners by Small Business Majority, 65% raised their prices, 37% delayed business investments, 20% froze hiring and 8% laid off workers. Again, small sample, but you can see the pattern.
Why It Happens
1. Tariffs and supply costs
Imports got more expensive in 2025 and the rules keep changing. On February 20, 2026 the Supreme Court said the president cannot use IEEPA to put tariffs on imports. After that, a temporary 10% import surcharge under Section 122 started on February 24, 2026. That surcharge expired on July 24, 2026. Other tariffs, like Section 232 and 301, are still a separate matter.
Even so, owners already paid a lot. The Center for American Progress found that small-business importers paid an average of $306,000 more in tariff costs from March 2025 through February 2026. And you don't need to import directly to feel it. If your supplier imports, the cost reaches you in the price list. 54% of owners in the Small Business Majority poll said higher cost of supplies and inventory was a major challenge.
2. Health insurance
This one hurts owners who give coverage to staff. Small group insurers asked for a median 11% increase going into 2026. For 2027 it looks worse. Nearly 300 insurers reported a median proposed increase of 14% for small group plans next year. KFF says that 14% is a median of proposed rates, not weighted by enrollment and final rates can differ by state and plan. Insurers point to rising medical costs, specialty drugs and healthier groups leaving fully insured plans.
3. Hiring is hard, even when wages are not the top complaint
This part is a bit surprising. Labor costs as the top problem is actually going down. In NFIB's September jobs report, only 6% named labor costs as their single most important problem, the lowest since December 2020. But finding workers is still hard. 26% said labor quality or availability was their top problem and 32% had job openings they could not fill. Also, a net 28% of owners were still raising pay. So the cost is not just wages. It is also open jobs, overtime, training and people leaving.
4. Borrowing costs more
The Fed went up again. On September 16, 2026 it raised the target range by a quarter point, to 3¾ to 4 percent and said inflation remains elevated. Business credit lines and loans can get more expensive when this happens, depending on the loan type. For an owner who already runs on credit, that is one more bill.
5. Not much cash to absorb shocks
If a business has less than 3 months of cash, one bad quarter can force bad choices. This is why a cost increase that looks small on paper can feel big.
Not everything is going up
Commercial insurance is one place with some good news. Marsh reported that the U.S. overall commercial insurance rate fell 2% in Q2 2026 and global property rates fell much more. But be careful. Marsh's index leans toward larger accounts and casualty was the one line that went up. A small shop may see something different. Still, it means your business insurance may be worth shopping.
What Usually Goes Wrong
Raising prices all at once or never. Big sudden jumps scare customers. Waiting too long makes you lose money every sale.
Cutting the wrong thing. Cutting the one thing that brings customers (service quality, key staff, all marketing) can cost more than it saves.
Ignoring small bills. Ten small subscriptions you forgot about can add up like one big bill.
Paying suppliers late without telling them. This damages trust and may remove your discounts.
Waiting for the renewal letter. Health insurance and loan terms are easier to change before the deadline than after.
No cash buffer. Every shock turns into a loan.
The Solution
None of these steps fix everything. Together, they can take some pressure off.
Step 1: Know your real numbers
List every cost for the last 3 months. Mark the top five. Most owners find that 3 or 4 items are most of the problem. Fix those first. Don't start with the small stuff.
Step 2: Talk to your suppliers early
SBDC advisors say owners should contact suppliers early, when they see a cash flow problem and look at renegotiating payment terms. Suppliers often prefer a long-term customer with new terms over losing the customer. Ask for a volume discount, longer payment time or a lower price for paying fast. Also get one or two backup quotes. This gives you something to compare.
Step 3: Raise prices in a planned way
If most of your costs went up, some of it has to go to the price. Small, clear increases are easier than one big jump. Tell regular customers before it happens. Raise prices first on the items or services where your margin is lowest.
Step 4: Look again at health insurance
If you give coverage, ask a broker who works with small groups and ask before renewal. Options owners often look at include higher-deductible plans, level-funded plans or reimbursing employees for their own coverage (QSEHRA for small employers or ICHRA). These can lower the monthly bill. But there are trade-offs. Level-funded plans are generally exempt from some state and ACA rules and they work best for groups with healthier staff. Talk to a broker and your accountant before changing anything. This is not a decision to make in one afternoon.
Step 5: Shop other business insurance
Property and cyber rates have been soft in the market. Ask your agent for quotes from two or three other companies. Don't just look at price. Check what's covered and the deductible.
Step 6: If you import, check tariff refunds
If your business paid IEEPA tariffs, you may have a refund claim. But refunds are not automatic and only IEEPA duties are refundable, not Section 232 or 301 duties. Talk to your customs broker or a trade lawyer about it. If you bought from a supplier who paid the duty, ask your contract's terms too.
Step 7: Keep the staff you have
Hiring is hard right now, so people leaving costs money. Small things like a better schedule or steady hours can cost less than hiring and training again.
Step 8: Build a cash cushion slowly
Even a little cash helps. Put a fixed small amount aside each week. Try to reach one month of costs first, then go bigger. If you must borrow, compare the full cost, not just the monthly payment.
What to Check
After 60 to 90 days, look again:
Did your top five costs go down, stay the same or go up?
Are your margins better on the products you raised prices for?
Did you lose regular customers after the price change?
Do you have more days of cash than before?
Did you get new terms from suppliers in writing?
If nothing changed, that is also information. It means the problem may be somewhere else.
When These Steps May Not Work
If your costs rose a lot but your customers can't pay more, price changes may not fix it. You may need to change what you sell.
Tariff rules are still in court, so costs can move again.
Health plan changes can backfire if one employee has big medical needs.
Cutting costs can't fix a business that has a sales problem.
When to Get More Help
Talk to your accountant first, because they know your real numbers. For free or low-cost guidance, the SBA and your local Small Business Development Center can help with cash flow planning. For tariff refunds, use a customs broker or a trade lawyer. This article is general information. It is not legal, tax or financial advice.
Short Conclusion
Costs are going up in many places at once: supplies, health insurance, hiring and borrowing. No single move fixes it. Start with your top five costs, talk to suppliers, raise prices with a plan and keep a little cash aside.
FAQs
Why are my business costs still rising when inflation looks lower?
Inflation is not the only thing. U.S. consumer prices were still up 3.4% year over year in August 2026. Also, some costs, like health insurance, rise faster than general inflation. Past price increases also don't go back down.
Are tariffs still raising costs in October 2026?
It depends on what you buy and where it comes from. The IEEPA tariffs were struck down and the Section 122 surcharge ended in July, but other tariffs remain and suppliers may still carry old costs. The rules are changing, so check your own product category.
Should I raise prices or cut costs first?
Usually both, but look at costs first. Fix the five largest bills, then see how much price change you still need.
Can small businesses get tariff refunds?
Possibly, if you paid IEEPA duties as the importer. It is not automatic. A customs broker or trade lawyer can tell you what applies.
Is dropping health insurance for staff a good idea?
It is a big decision with real effects on hiring and staff. Look at other options first, like different plan types or reimbursement and talk to a broker and accountant.
Where can I get free help?
The SBA and your local Small Business Development Center offer guidance on cash flow and planning.
Share this story with your network
Direct citation and sharing for this investigative report.
View Point Spot
Editor-in-Chief
View Point Spot is a place for ideas, stories, insights and different points of view. We share useful, interesting and easy-to-understand content across a wide range of topics, helping readers discover something new and see the world from a different perspective.
Related Coverage & Dispatches
More in Business & Markets →
What Makes People Choose One Brand Over Another?
What makes people pick one brand instead of another? Here's a simple look at trust, price, habit and the small details that actually matter.
 Afshan YasmeenSep 11, 2026

Why Is Customer Trust More Valuable Than Cheap Prices?
Cheap prices bring one-time buyers. Customer trust brings repeat ones. Here's why trust builds a stronger, more stable business over time.
Afshan YasmeenSep 11, 2026
How Do Small Businesses Decide What to Charge for a Product?
A clear look at how small businesses set product prices, including the main pricing methods, common mistakes and how to pick a price that actually works.
Afshan YasmeenSep 11, 2026Reader Discussion (0)
No comments yet. Be the first to start the discussion!