How to Build a Simple Monthly Budget That You Can Actually Follow
A step-by-step guide to building a monthly budget that fits real life. Simple steps, common mistakes to avoid and how to stick with it long-term.
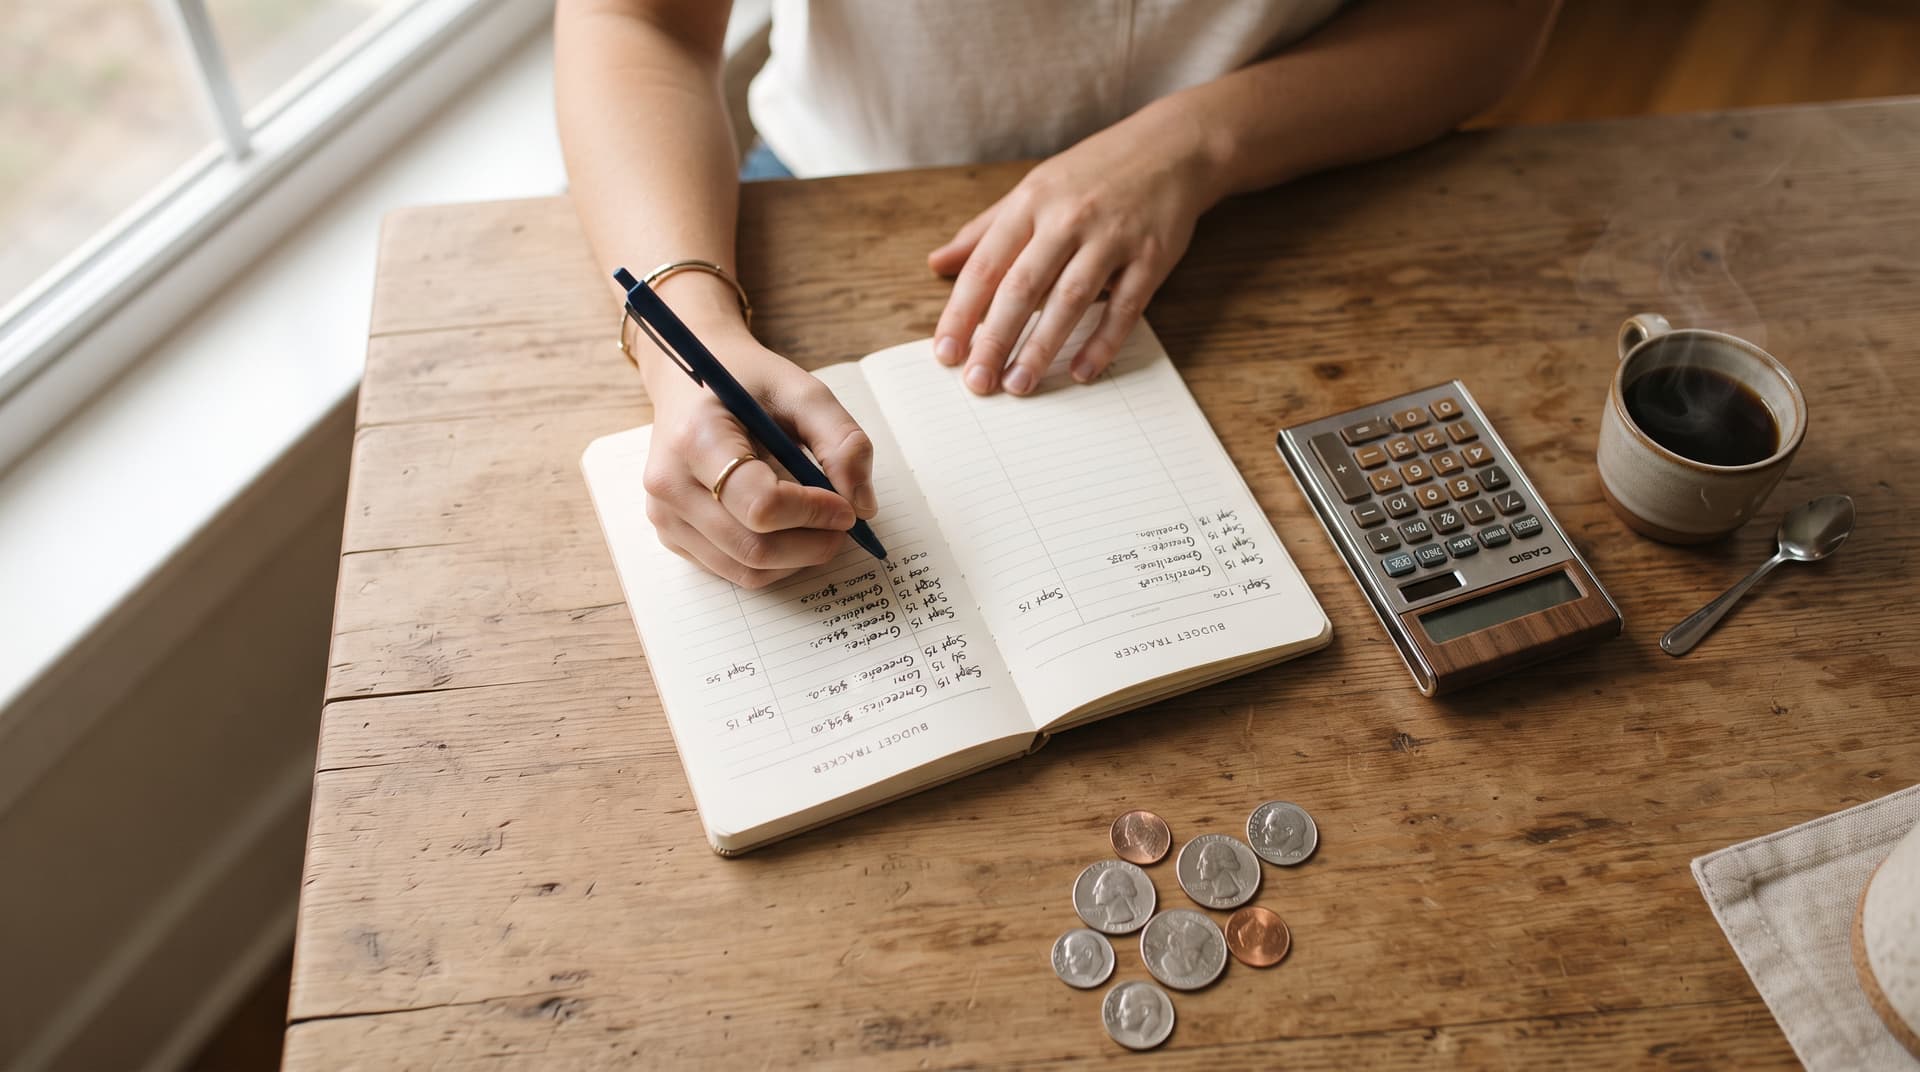
Most budgets fail for one simple reason: they are too complicated to keep up with. People download a spreadsheet with twenty categories, fill it in for two weeks and then quietly stop. This guide skips the complicated part. It shows you how to build a budget with a small number of steps, using numbers you already know.
Why Most Budgets Don't Last
Before building your budget, it helps to know why past attempts may not have worked.
Common reasons budgets fall apart:
Too many categories to track every day
Numbers that don't match how you actually spend
No plan for irregular costs, like car repairs or gifts
Guilt after one bad week, which leads to quitting entirely
A budget only works if it's simple enough to check in five minutes. That's the goal here.
Step 1: Find Out What You Actually Earn
Start with your real monthly income, not your yearly salary divided by twelve.
If your pay is the same every month, use that number. If it changes because of overtime, freelance work or commissions look at your last three months of income and use the lowest amount. This gives you a safer starting point instead of assuming a good month is a normal month.
If you have more than one source of income, add them together.
Step 2: List Your Fixed Expenses
Fixed expenses are the ones that stay roughly the same each month. These usually include:
Rent or mortgage
Loan payments
Insurance
Phone and internet bills
Subscriptions
Go through your bank statement or bill history from the last month and write these down with real numbers, not rough guesses. This step usually takes the most time, but it's worth doing properly. Once it's done, you won't need to redo it often.
Step 3: Estimate Your Variable Expenses
Variable expenses change from month to month. Common ones include:
Groceries
Fuel or transport
Eating out
Personal care
Entertainment
For these, look at what you spent last month, then round the number up slightly. It's better to plan for a little more than to run short halfway through the month.
Step 4: Use a Simple Split, Not a Complicated One
A detailed 20-category budget looks organized, but it's hard to maintain. A simpler approach works better for most people.
One common method is the 50/30/20 rule:
Category Percentage of Income What It CoversNeeds50%Rent, bills, groceries, transportWants30%Eating out, hobbies, entertainment Savings and debt20%Savings, extra loan payments
This isn't a fixed rule. If your rent is high compared to your income, your split might look more like 60/20/20 and that's fine. The percentages are a starting point, not a requirement.
Step 5: Set Aside Money for Irregular Costs
This is the step most budgets skip and it's often what causes them to fail.
Some expenses don't happen every month, but they still happen: car maintenance, medical visits, birthdays, annual subscriptions. If you don't plan for these, they always feel like a surprise, even though they're predictable in general.
A practical way to handle this is to set aside a small fixed amount each month even a modest one into a separate savings space just for irregular costs. When one of these expenses comes up, you pay from that fund instead of pulling money from your regular budget.
Step 6: Choose One Way to Track Spending
You don't need multiple tools. Pick one method and stick with it:
A basic spreadsheet
A notes app where you log expenses
A budgeting app connected to your bank
A simple notebook
The best tracking method is the one you'll actually use. A notebook you check daily is more useful than an advanced app you open once a month.
Step 7: Review It Weekly, Not Daily
Checking your budget every day can feel stressful and is usually unnecessary. A short weekly check is often enough.
During this check, ask three questions:
Am I on track for my fixed expenses?
Is my variable spending close to what I planned?
Do I need to adjust anything for the rest of the month?
This keeps you aware of your spending without turning it into a daily chore.
Common Mistakes to Avoid
Making the budget too strict. If every category is tight, one unexpected cost throws off the whole plan.
Ignoring small purchases. Coffee, snacks and small app purchases add up faster than people expect.
Comparing your budget to someone else's. Income, rent and family size are different for everyone. A budget that works for a coworker may not fit your situation.
Giving up after one bad month. A budget is not a test you pass or fail. It's a plan you adjust as you go.
What to Do When the Budget Doesn't Match Reality
Sometimes, after tracking for a month, you'll notice your budget doesn't match your actual spending. This is normal, especially in the first two or three months.
When this happens, don't throw out the whole plan. Adjust the numbers based on what you actually spent, not what you hoped to spend. A budget built on real numbers is more useful than one built on good intentions.
FAQ
Do I need a budgeting app to do this? No. A budgeting app can help with tracking, but the method in this guide works with a notebook, a spreadsheet or your phone's notes app.
What if my income changes every month? Use your lowest recent month as your base income. This gives you a more realistic and safer starting point.
How strict should the budget be? Strict enough to guide your spending, but not so tight that one unplanned expense breaks the whole plan. Some flexibility in the "wants" category usually makes a budget easier to follow long-term.
How long does it take before a budget feels normal? For most people, it takes two to three months before checking a budget feels like a habit instead of a task.
What Matters Most
A budget doesn't need to be detailed to be useful. It needs to be honest about your income, realistic about your expenses and simple enough to check regularly. Start with the steps above, adjust the numbers as you learn more about your spending and give yourself room to make changes along the way.
Related Topics:
Share this story with your network
Direct citation and sharing for this investigative report.
Noman Maken
Senior Software Engineer
I’m Noman Maken, a Senior Software Engineer at UMT and a freelance systems architect with 8+ years of experience. I build scalable software, APIs, databases, and modern web applications. My main expertise is in Next.js, React, Node.js, databases, microservices, and Generative AI. I focus on writing clean, secure, reliable, and practical software.
Related Coverage & Dispatches
More in Business & Markets →
Why Small Businesses in the U.S. Struggle With Rising Operating Costs and What They Can Do
This article explains why many U.S. small businesses are paying more to run every month in 2026. It covers tariffs, health insurance, hiring, borrowing cost and low cash. Then it gives practical steps owners can try, how to check if they work and when they may not be enough.
 View Point SpotOct 5, 2026

What Makes People Choose One Brand Over Another?
What makes people pick one brand instead of another? Here's a simple look at trust, price, habit and the small details that actually matter.
 Afshan YasmeenSep 11, 2026

Why Is Customer Trust More Valuable Than Cheap Prices?
Cheap prices bring one-time buyers. Customer trust brings repeat ones. Here's why trust builds a stronger, more stable business over time.
Afshan YasmeenSep 11, 2026Reader Discussion (0)
No comments yet. Be the first to start the discussion!